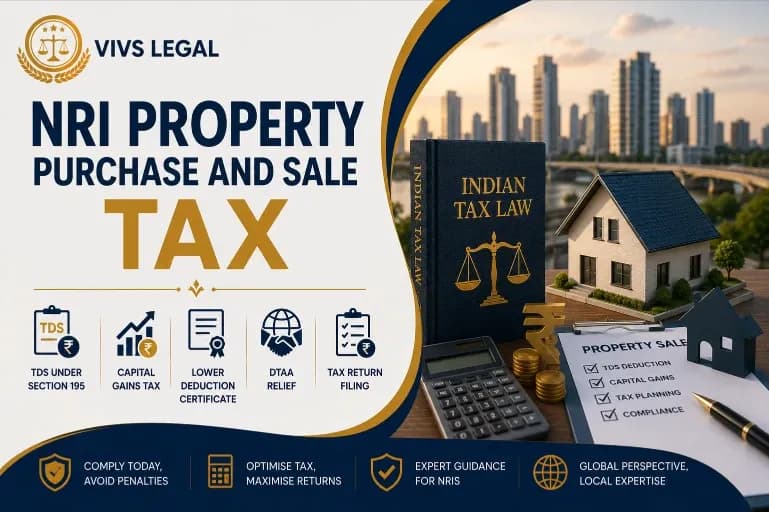
- The buyer deducts tax at source and needs a TAN to deposit it.
- Long-term gains on property held over 24 months are taxed at 12.5%, plus surcharge and cess, without indexation for NRIs.
- A lower deduction certificate can reduce TDS to the actual tax.
- Proceeds are repatriated within FEMA limits with the required forms.
On this page
TDS on sale of property by NRI: who deducts and how
- The buyer obtains a TAN.
- The buyer deducts tax from the payment at the non-resident rate.
- The buyer deposits it and files the quarterly return.
- The buyer issues a TDS certificate to the seller.
Under the Income-tax Act, 2025, from 1 April 2026, the provisions are renumbered but the scheme continues; check the current forms with a tax adviser.
Capital gains tax on property sale by NRI
| Holding period | Type | Tax for NRIs |
|---|---|---|
| Over 24 months | Long-term | 12.5% of the gain, plus surcharge and cess, without indexation |
| Up to 24 months | Short-term | At slab rates |
Exemptions for reinvestment in another residential property or specified bonds may reduce the tax; confirm eligibility with your tax adviser.
What is a lower deduction certificate?
A certificate from the tax department allowing the buyer to deduct tax at a lower rate, or not at all, based on the seller's actual liability. Apply well before the sale with the purchase and sale details and cost of improvement.
How are the sale proceeds repatriated?
Proceeds from property bought with NRE or FCNR funds can be repatriated up to the amount paid in foreign exchange, for up to two residential properties. Other proceeds go through the NRO account, within the annual limit of USD 1 million, with the required forms and a chartered accountant's certificate.
NRI taxes on property in India: other points
- Rent from Indian property is taxable in India, with tax deducted by the tenant.
- Double taxation is usually avoided through the tax treaty with your country of residence.
Founder and Managing Partner, VIVS Legal. BLS, LL.B, LL.M, PGDBM, JAIIB.